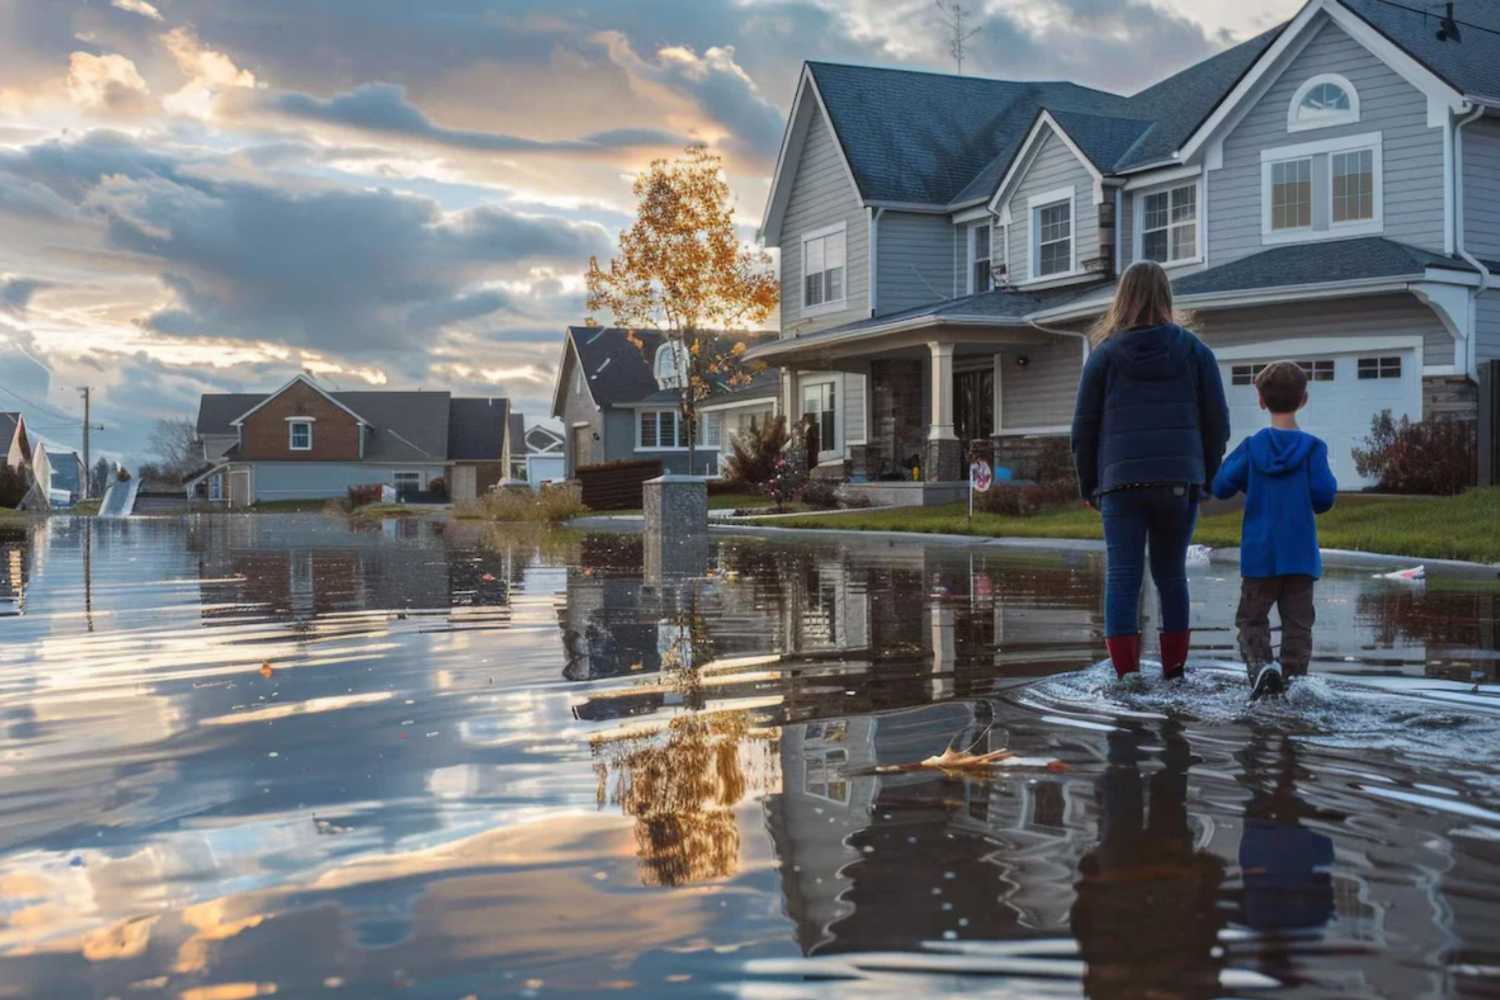
Your home's flood risk can change over time, even if you have lived in the same neighborhood for years. Updated flood maps, new construction, drainage changes and shifting weather patterns can influence how communities assess flood exposure. For homeowners, these changes can affect insurance needs, property planning and future costs. Understanding your property's flood risk can help you make informed decisions about protecting your home and finances.
Flood zones identify areas with different levels of flood risk, helping communities, homeowners and insurers assess potential exposure. In the United States, FEMA periodically updates its Flood Insurance Rate Maps as new information becomes available. If your property's designation changes, it may affect building requirements, insurance considerations and how you prepare for flooding. Check FEMA's Flood Map Service Center to review the latest available map information for your address.
Your property's flood zone can influence your insurance requirements and costs. If your home is in a high-risk flood zone and you have a mortgage from a federally regulated or insured lender, flood insurance may be required. However, flood risk is not limited to high-risk zones, and homeowners outside these areas can also experience flooding. Reviewing your property's exposure can help you decide whether additional protection makes sense for your circumstances.
Many homeowners assume their standard insurance policy covers every type of water damage, but most standard homeowners policies do not cover damage caused by flooding. Flood insurance generally provides separate protection for eligible flood-related damage to your home's structure and certain belongings, subject to policy terms and limits. Understanding this distinction can help you identify potential coverage gaps before a flood occurs.
Homeowners may be able to obtain flood insurance through the National Flood Insurance Program (NFIP) or private insurers, depending on availability and eligibility. Coverage limits, deductibles, exclusions and pricing can vary. Review what each policy covers, including structural features, personal belongings and any applicable restrictions, so you understand the protection available for your property.
Insurance is only one part of preparing your home for flooding. Keep gutters and drainage areas clear, maintain sump pumps where applicable and consider elevating vulnerable equipment or using flood-resistant materials when renovating. Check local flood guidance and consult qualified professionals to identify improvements suitable for your property. These steps may help reduce damage, although they cannot eliminate flood risk.
Changing flood maps are a useful reminder to review your property's risk and insurance needs periodically. By checking updated maps, understanding your coverage and preparing your home, you can make more informed decisions about protecting your property and financial future.